
Financial advisors can save you from costly mistakes — or cost you tens of thousands in unnecessary fees. The industry has a confusing mix of fiduciaries, commission-based salespeople, robo-advisors, and everything in between. How do you know who to trust with your money?
Types of Financial Advisors
| Type | How They’re Paid | Standard | Watch Out For |
|---|---|---|---|
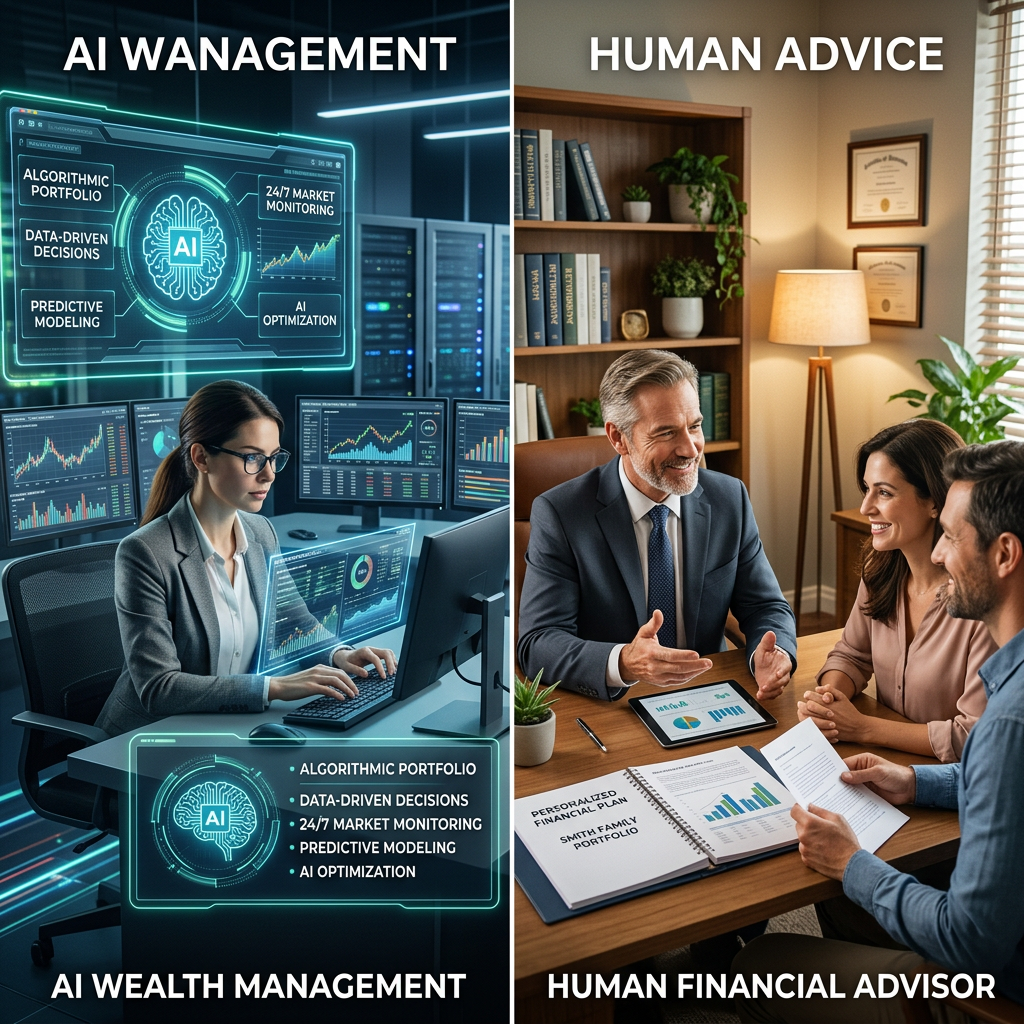
| Fee-Only Fiduciary | Flat fee or % of AUM | Must act in your best interest | High AUM minimums |
| Fee-Based | Fees + commissions | Fiduciary sometimes | Hidden commission incentives |
| Commission-Based | Product sales commissions | “Suitability” (lower standard) | Sells you expensive products |
| Robo-Advisor | 0.25–0.50% of AUM | Algorithm-based | Limited personalization |
Fee-Only vs. Commission-Based: Why It Matters
A fee-only fiduciary must legally act in your best interest. A commission-based advisor only needs to recommend “suitable” products — which may have high fees that benefit them, not you. The difference can cost you $200,000+ over 30 years on a $500K portfolio.
Always ask: “Are you a fiduciary 100% of the time?” If they hesitate, walk away.
What Financial Advisors Actually Cost
| Fee Structure | Typical Cost | On $500K Portfolio |
|---|---|---|
| AUM (% of assets) | 0.5–1.0% | $2,500–$5,000/year |
| Flat fee (annual) | $2,000–$7,500 | Fixed regardless of assets |
| Hourly | $150–$400/hour | Pay only for time used |
| Per-plan | $1,000–$3,000 | One-time comprehensive plan |
| Robo-advisor | 0.25% | $1,250/year |
When You NEED a Financial Advisor
- Complex tax situations: Stock options, RSUs, rental income, business ownership
- Major life transitions: Inheritance, divorce, retirement, selling a business
- Estate planning: When your net worth exceeds $1M+
- Behavioral coaching: You know you panic-sell during crashes
- Tax optimization: Roth conversions, tax-loss harvesting, charitable giving strategies
When You DON’T Need One
- Simple situation: You have a 401(k), IRA, and straightforward income
- DIY knowledge: You understand asset allocation, tax-advantaged accounts, and rebalancing
- Small portfolio: Under $100K — a robo-advisor or target-date fund is sufficient
- You enjoy managing money: If you find personal finance interesting, you can do this yourself
Red Flags to Avoid
- Pushes whole life insurance or annuities (high commissions)
- Won’t disclose all fees in writing
- Guarantees specific returns
- Uses high-pressure sales tactics
- Won’t sign a fiduciary oath
- Recommends proprietary funds with high expense ratios
How to Find a Good Advisor
- Search NAPFA.org (fee-only fiduciaries only)
- Check their credentials: CFP® (Certified Financial Planner) is the gold standard
- Verify on BrokerCheck.FINRA.org for disciplinary history
- Interview at least 3 before choosing
- Ask for a sample financial plan to see their work quality
Frequently Asked Questions
Can I just use a robo-advisor?
For basic investing (asset allocation, rebalancing, tax-loss harvesting), yes. Wealthfront and Betterment are excellent for straightforward situations. Add a human advisor when your situation becomes complex.
Is 1% AUM fee fair?
On a $200K portfolio, 1% ($2,000/year) is reasonable for comprehensive planning. On a $2M portfolio, 1% ($20,000/year) is excessive — negotiate or find a flat-fee advisor.
🚀 Take Control of Your Finances with Richify
Get your financial baseline before meeting an advisor. Take the free Financial Quiz to understand your current financial health, then track your portfolio to see if your advisor is adding value.
📱 Download the Richify app for DIY financial tracking and tools.
Disclaimer: This article is for educational purposes only. It does not constitute financial advice.

Leave a Reply