
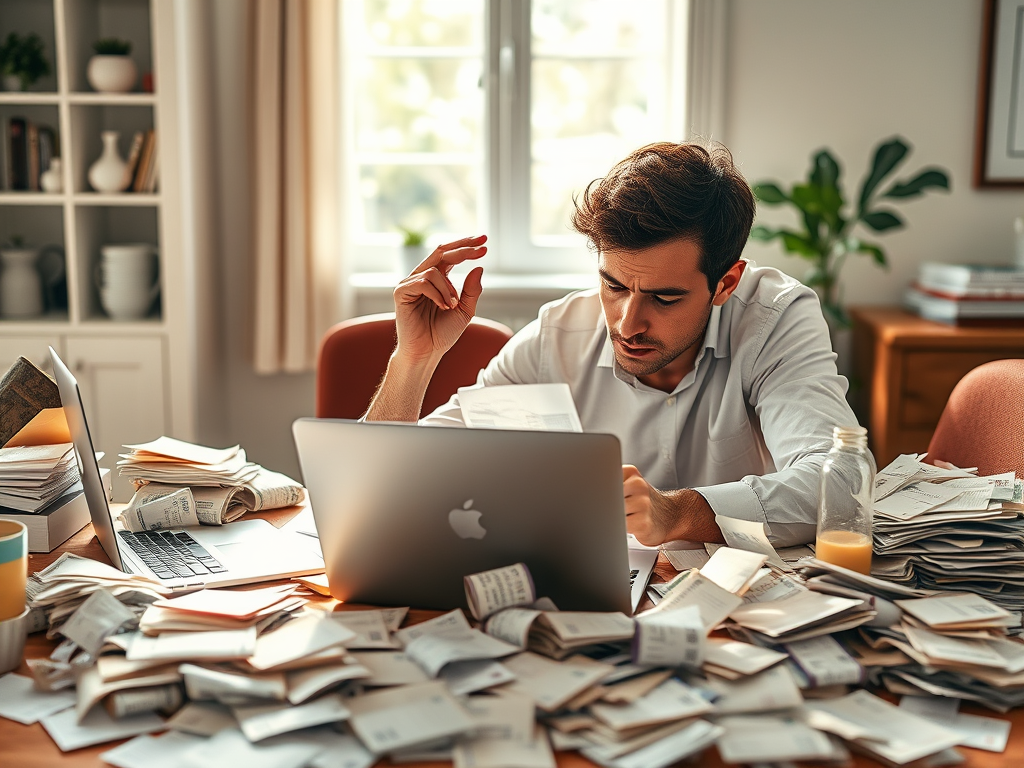
A brutally honest experiment in personal finance that revealed uncomfortable truths about my spending habits (and probably yours too)
Day 1 started simple enough. Coffee: $4.50. Lunch: $12.87. A “quick” Target run: $67.32 (how does that even happen?). By Day 3, I was already questioning my life choices. By Day 30, I had uncovered some uncomfortable truths about my relationship with money.
I’m not talking about the usual “I spent too much on lattes” revelation that every personal finance article loves to preach. This experiment revealed something far more interesting—and actionable.
Why I Started This Insane Experiment
Like most people, I thought I had a pretty good handle on my finances. I checked my bank account occasionally, paid my bills on time, and figured that as long as I wasn’t overdrafting, I was doing fine.
Then I read a statistic that stopped me cold: 65% of Americans couldn’t tell you within $500 how much they spent last month.
Was I part of that statistic? I decided to find out.
The Rules
To make this legitimate, I set strict parameters:
- Track everything. Not just bills and big purchases, but every. Single. Transaction.
- Categorize immediately. No waiting until the end of the day.
- Include hidden costs. That free trial that auto-renewed? Tracked.
- Be honest. No conveniently “forgetting” embarrassing purchases.
- No behavior changes. This was about awareness, not restriction.
I used a simple spreadsheet with categories: Housing, Transportation, Food (groceries), Food (dining out), Entertainment, Subscriptions, Health, Shopping, and Miscellaneous.
Week 1: The Awareness Shock
Total Spent: $847.32
The first week was brutal. Not because I spent a lot, but because I became hyper-aware of every purchase decision.
The “Decision Fatigue” Purchase Pattern I noticed something fascinating: My worst spending happened between 4-7 PM. After a full day of work decisions, my brain defaulted to the path of least resistance. Takeout instead of cooking. Impulse Amazon purchases. Unnecessary convenience store stops.
This wasn’t about laziness—it was about cognitive depletion.
The Subscription Graveyard Within the first three days, I discovered 7 subscriptions I’d forgotten about:
- A meditation app I used twice ($12.99/month)
- Cloud storage I didn’t need ($9.99/month)
- A music streaming service (I already had Spotify) ($10.99/month)
- Two “free trials” that auto-renewed ($19.98 combined)
- A gym membership I hadn’t used in 4 months ($45/month)
Total waste: $98.95/month, or $1,187.40 per year on services providing zero value.
Week 2: The Social Spending Trap
Total Spent: $923.18
Week 2 revealed my most expensive blind spot: social obligation spending.
Three “casual” hangouts with friends cost $287. Not because we went anywhere fancy, but because each one involved:
- Dinner out: $45-65 per outing
- Drinks after: $30-40
- Transportation: $15-25 (parking or rideshare)
- The inevitable “let’s grab dessert”: $12-18
I love my friends. But I was spending $1,000+ per month on social activities I only moderately enjoyed because I was on autopilot.
The “Yes Default” Problem I realized I’d developed a “yes default” to invitations. Someone suggests drinks? Yes. Dinner invite? Yes. Concert I’m lukewarm about? Yes.
Not because I wanted to go, but because saying yes required zero mental energy.
Week 3: The Grocery Store Illusion
Total Spent: $734.56
I considered myself pretty good at groceries. I meal-planned (sometimes). I used coupons (occasionally). I bought store brands (when convenient).
The tracking revealed a different story.
My Actual Grocery Patterns:
- Weekly “big shop”: $120-140
- “Quick” midweek trips: 3-4 trips × $25-40 = $100-160
- Total grocery spending: $220-300/week
But here’s the kicker: I was still ordering takeout 3-4 times per week at $15-30 per meal.
I was spending $300/week on groceries and another $200/month on food delivery. For one person.
The Food Waste Factor I started checking my fridge before each grocery run. About 30% of my previous week’s “healthy” purchases were rotting in the crisper drawer. I was literally throwing away $60-90/month.
Week 4: The Convenience Tax
Total Spent: $812.47
The final week brought the most valuable insight: I was paying an enormous “convenience tax.”
Examples:
- Gas station water bottles instead of refilling: +$4/day = $120/month
- Last-minute Amazon orders with fast shipping: +$30-50/month
- Convenience store snacks vs. buying in bulk: +$40/month
- Peak-time rideshares vs. planning ahead: +$60/month
- Late fees on bills I forgot to automate: +$15/month
Total convenience tax: ~$265/month or $3,180/year
The Numbers: 30-Day Totals
CategoryAmount% of TotalHousing (rent + utilities)$1,45044.8%Food (groceries)$84726.2%Food (dining out)$39812.3%Transportation$2878.9%Entertainment$1454.5%Shopping$892.8%Subscriptions$1123.5%Total$3,328100%
The Uncomfortable Realizations
1. My “Small” Purchases Were Actually Huge I worried about big purchases like rent and car payments. But my real money leak was the $8-25 transactions happening 3-5 times daily.
2. Convenience Was Costing Me $3,000+/Year Every “it’s just a few bucks” decision compounded into serious money.
3. I Was Buying Solutions to Problems I Created Expensive last-minute lunch because I didn’t meal prep. Rideshare because I didn’t plan my schedule. Premium shipping because I procrastinated.
4. Tracking Changed My Behavior (Unintentionally) Despite my rule about not changing behavior, awareness alone reduced my spending by ~15% by Week 4. Simply knowing I’d have to categorize and write down a purchase made me pause.
5. I Had No “Joy” Metrics I could tell you what I spent on dining out, but not which meals actually made me happy. Some $50 dinners were memorable experiences. Others were forgettable. But they cost the same.
What I Changed Immediately
Quick Wins (Month 1):
- Canceled forgotten subscriptions: +$98.95/month saved
- Automated bills to avoid late fees: +$15/month saved
- Bulk-bought convenience items: +$40/month saved
- Started meal prepping Sundays: +$200/month saved
Total immediate savings: $353.95/month or $4,247.40/year
Longer-Term Changes:
- The 24-Hour Rule: Any non-essential purchase over $50 requires 24-hour wait
- Social Spending Boundaries: Set monthly “social budget” and suggested low-cost alternatives
- Weekly Grocery Check: Take fridge inventory before shopping
- Subscription Audit: Quarterly review of all recurring charges
- Joy Tracking: Rate purchases 1-10 for happiness delivered
The Bigger Picture: What This Really Taught Me
This experiment wasn’t about deprivation or becoming obsessive about money. It was about intentionality.
Before: Money flowed out unconsciously, following the path of least resistance.
After: Every dollar became a choice. Not a stressful choice, but a conscious one.
The question changed from: “Can I afford this?” (usually yes)
To: “Does this purchase align with what I actually value?” (often no)
The Psychology Behind It All
Why do we spend unconsciously?
1. Decision Fatigue We make 35,000 decisions daily. Our brains conserve energy by defaulting to habits—including spending habits.
2. Present Bias Our brains are wired to prioritize immediate gratification over future benefits. The $5 coffee feels good now; the $1,800/year we’d save by making coffee at home is abstract.
3. Mental Accounting We treat money differently based on how we categorize it. “Found” $20 gets spent differently than “earned” $20, even though it’s the same money.
4. The Endowment Effect Once we imagine owning something (especially with online shopping), our brain treats not buying it as a loss rather than the status quo.
Your 30-Day Challenge
Want to try this yourself? Here’s your simplified version:
Week 1: Just track. Don’t judge, don’t change—just observe.
Week 2: Categorize your spending. Look for patterns.
Week 3: Identify your top 3 spending leaks.
Week 4: Experiment with one change per week.
Tools You’ll Need:
- A simple spreadsheet or app (I used Google Sheets, but Richify offers excellent tracking with AI insights)
- 2-3 minutes per day
- Honest with yourself
The Bottom Line
After 30 days of tracking every dollar, I didn’t become a penny-pinching minimalist. I became more intentional.
I still buy coffee out—but now it’s a deliberate treat, not a default. I still see friends—but we’ve found ways to connect that don’t always revolve around expensive restaurants. I still value convenience—but I’m aware of its price tag.
Most importantly: I found $4,200+ per year hiding in my spending patterns. Money I didn’t even know I was wasting.
That’s not about willpower or deprivation. That’s about awareness.
And awareness, it turns out, is worth far more than I ever spent on it.
What’s Next?
The experiment doesn’t end at Day 30. I’m now tracking:
- Which purchases brought actual joy vs. which I don’t even remember
- How spending patterns change by day of week and time of day
- The relationship between stress levels and impulse purchases
- Whether budgeting in advance actually works (controversial!)
Your turn: What would you discover if you tracked every dollar for 30 days? Based on my experiment, I’m guessing it won’t be what you expect.
Ready to track your wealth across all asset types—not just expenses? Richify AI helps you manage stocks, crypto, real estate, and more with AI-powered insights. Start tracking smarter today.

Leave a Reply